
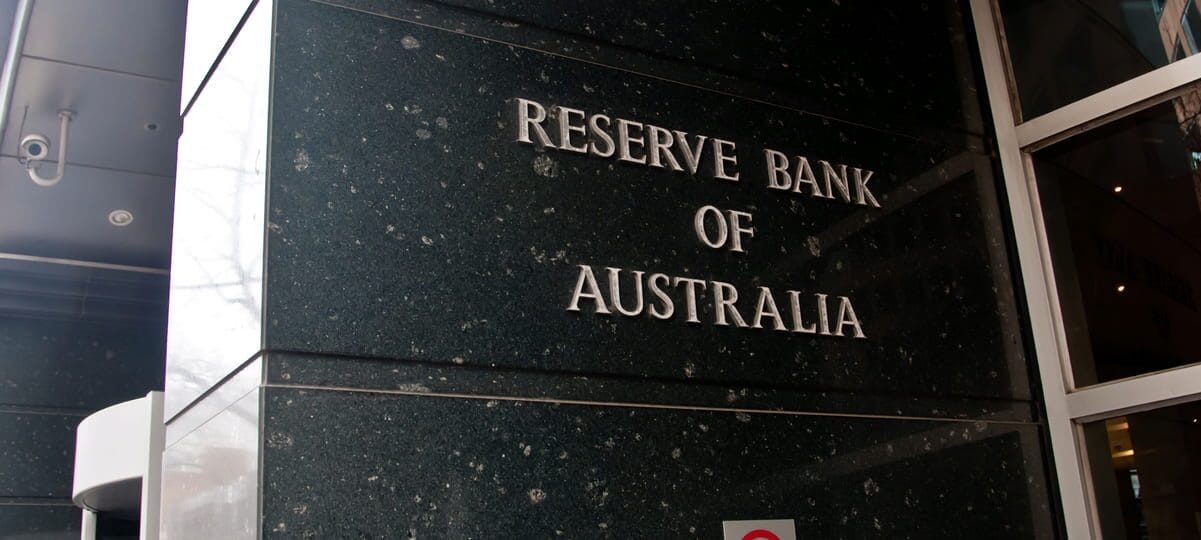
An Australia wage-price spiral is unlikely under current labor-market institutions, Reserve Bank of Australia board member Iain Ross said, arguing that recent data show little evidence of a self-reinforcing cycle.
Ross said his remarks represented his own views rather than a formal position of the nine-member Monetary Policy Board. He compared present wage-setting arrangements with the conditions that amplified inflation in the 1970s.
Australia Wage-Price Spiral Risk Differs From the 1970s
In his official RBA speech, Ross said Australian inflation rose from about 3% in 1969 to more than 16% in 1974, while male average weekly earnings growth reached 25%. Strong demand, rising inflation expectations and centralized wage-setting helped increases spread across industries.
Today’s system has fewer mechanisms for that rapid transmission. Modern awards mainly provide minimum standards, broad adjustments generally occur through an annual review and enterprise agreements limit new wage claims during their terms.
The average nominal term of enterprise agreements lodged in the year to March 2026 was three years. Because agreements expire at different times, only a portion of covered workers renegotiates wages in any quarter, slowing the pass-through from a temporary inflation shock.
Lower Union Density and Anchored Expectations Reduce Transmission
Ross said union membership has declined from slightly more than half of employees in the late 1970s to 13% today. The 2024 rate was 7.9% in the private sector and 33.2% in the public sector, while industrial disputes have also fallen sharply.
He cautioned that the relationship between unionization and wage growth is not simple. Still, the reduced ability of one settlement to establish economy-wide wage comparisons makes the current bargaining structure different from the earlier inflation episode.
Historical evidence across advanced economies also suggests that an acceleration in nominal pay does not automatically become a persistent spiral. Ross said only a small share of past episodes produced sustained acceleration in both wages and consumer prices.
Anchored inflation expectations provide another buffer, Ross said. The assessment will be tested by future wage, productivity and consumer-price data, particularly if energy or other external costs produce another prolonged inflation shock.
