
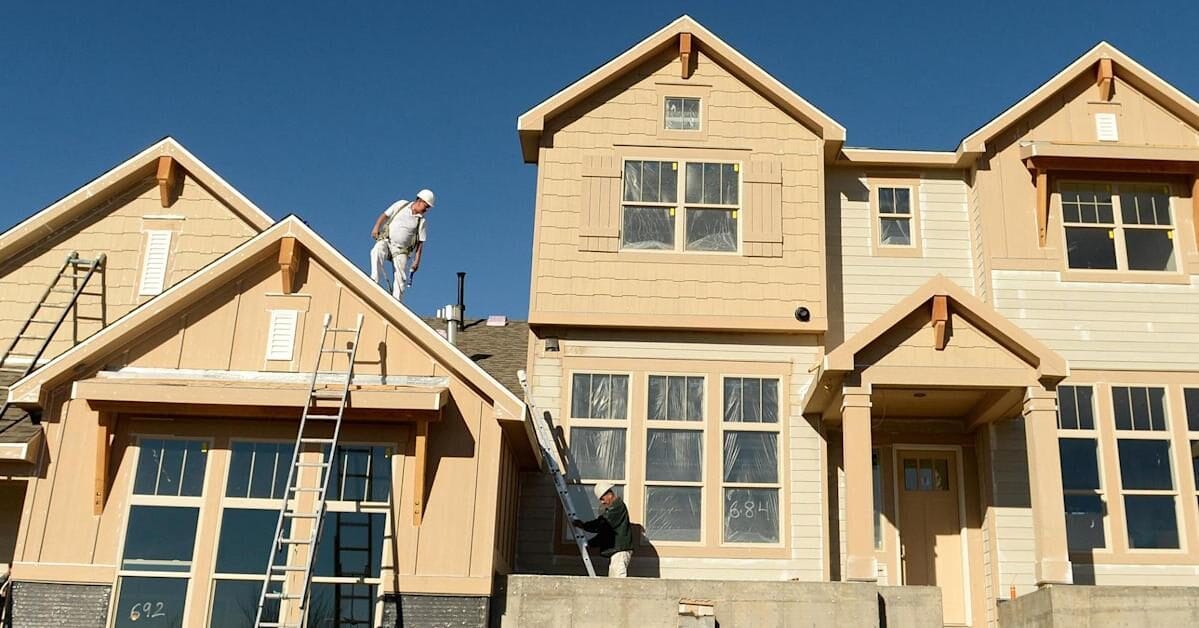
U.S. housing starts fell 2.6% in August to a seasonally adjusted annual rate of 1.275 million units, according to the latest Census Bureau release. The decline followed July’s rate of 1.309 million and points to a softer pace of new residential construction as builders face affordability and financing pressures.
The annualized figure is an estimate of the pace that would prevail over a full year if the month’s rate continued. It is not the number of homes physically started during August. Month-to-month housing data can also be volatile and are subject to revision.
U.S. Housing Starts Add to a Mixed Housing Picture
The official New Residential Construction release measures starts alongside building permits and completions. Those series help distinguish current groundbreaking activity from the future construction pipeline and the delivery of finished homes. A one-month decline in starts does not establish a lasting trend, but it is a timely signal about builder decisions.
The headline drop should also be read with the report’s sampling uncertainty in mind: the Census Bureau says it cannot conclude with statistical confidence that total starts changed from July. Single-family starts actually rose 7.6% to an annualized 918,000, while the rate for buildings with five or more units was 344,000. Building permits fell 2.7% to 1.394 million.
Earlier this week, a separate homebuilder sentiment survey weakened in September. The starts report provides a harder activity measure, although it covers August rather than September. Read together, the two releases warrant attention without assuming sentiment and actual construction move in lockstep.
Mortgage Rates Remain a Critical Variable
Builders are sensitive to both buyer financing and their own land and construction costs. Elevated mortgage payments can limit demand even where the need for housing remains substantial. At the same time, shortages of existing homes for sale may support new construction in some markets, producing uneven regional and property-type results.
U.S. housing starts will remain important to investors assessing the effects of Federal Reserve policy. The direction of longer-term yields, mortgage rates and household incomes will help determine whether August’s setback persists. The next releases on new-home sales and September construction activity should give a fuller view of the sector’s momentum.
